Corporate Relocations to Miami: Beyond the Narrative, What the Data Actually Shows
While headlines often trumpet a mass exodus to South Florida, a deeper dive into commercial real estate data reveals a more nuanced picture of corporate relocation trends. The influx is real, but its impact is highly concentrated and comes with distinct market pressures.
The narrative of a wholesale corporate migration to Miami has become a staple of business news cycles, particularly since 2020. Yet, for operators, investors, and brokers working in the trenches, the raw data presents a more granular, complex reality than the broad-stroke headlines suggest.
The Influx: A Closer Look at Absorption and Sector Concentration
Undeniably, Miami-Dade County has seen a significant uptick in corporate interest. Major players in finance, private equity, asset management, and increasingly, tech and venture capital, have established or expanded their presence. What the data consistently shows is that this influx is not evenly distributed across the commercial spectrum.
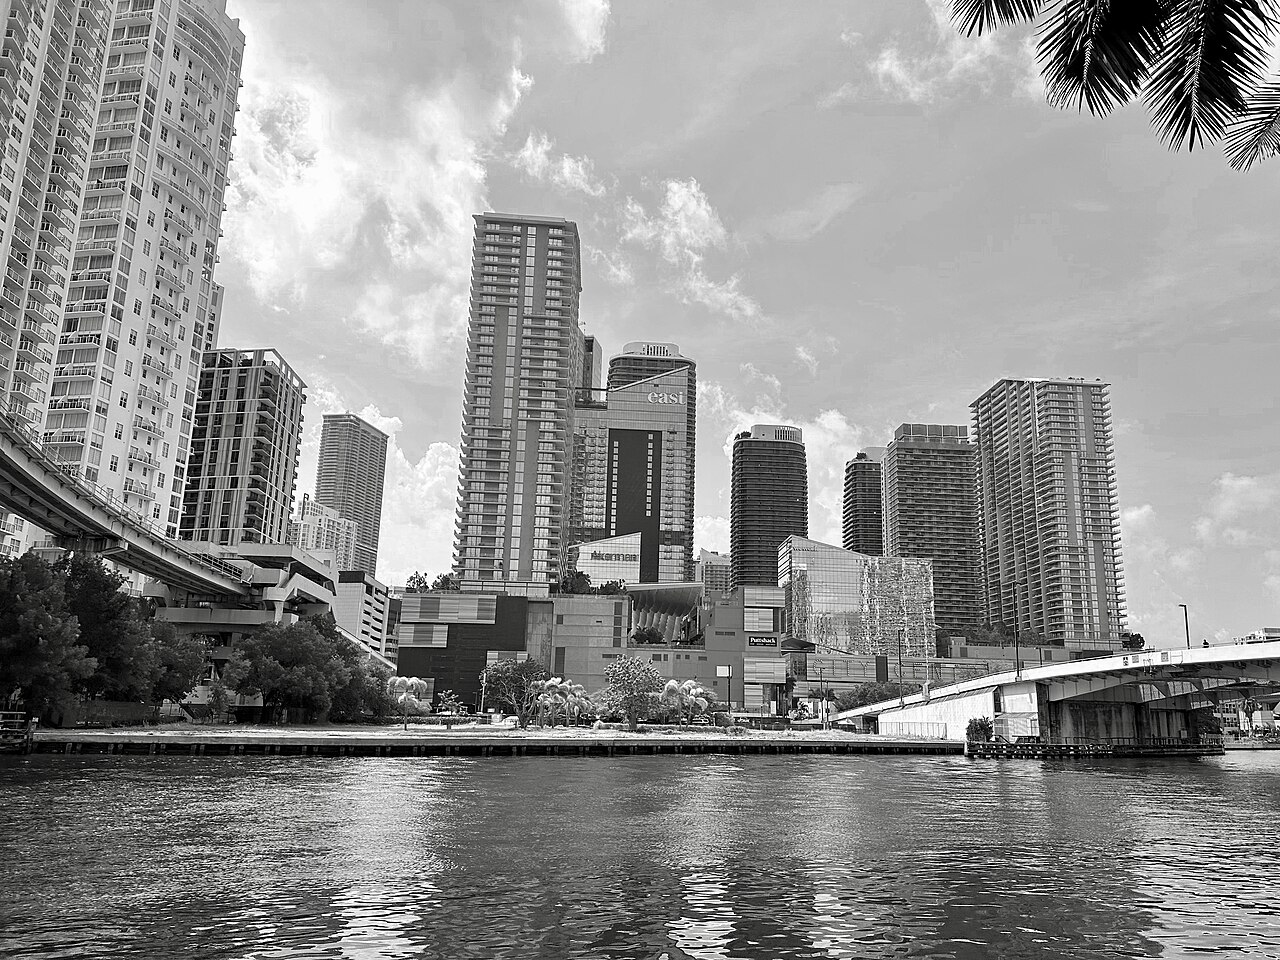
For example, Class A office absorption in Brickell and parts of downtown has remained robust, with year-to-date net absorption figures for Q3 2026 reaching approximately 450,000 square feet across the central business district. This is largely driven by financial services and family offices demanding prime space. We're seeing lease terms averaging 7-10 years for new entrants, often accompanied by significant tenant improvement allowances as firms seek bespoke build-outs. In contrast, Class B and C office markets, while benefiting indirectly from a tightening overall market, have not experienced the same transformative demand.
Wynwood and Midtown have become magnets for tech and creative enterprises, pushing asking rents for premium, converted warehouse space north of $75/SF NNN in some instances. These firms are often seeking the 'cool factor' and a specific talent pool, creating micro-markets with aggressive pricing and low availability for unique assets.
Submarket Pressures and Rental Dynamics
The concentration of demand has inevitably led to distinct market pressures. In Brickell, Class A vacancy rates have dipped below 8%, a significant compression from pre-pandemic levels. This scarcity, coupled with the high cost of new construction and development, has pushed average effective rents for prime Class A space above $90/SF annually. This isn't a market-wide phenomenon; submarkets like Doral, while stable, haven't seen the same explosive rental growth in their more traditional office parks, though industrial demand remains insatiable.
The story in Wynwood is similar for its specific product type. What was once an affordable alternative for startups and creative agencies is rapidly maturing into a high-cost innovation hub. Landlords are commanding premium rents, and cap rates for prime, stabilized assets are beginning to reflect this increased certainty of cash flow, often compressing into the low 5% range for institutional-grade product. Edgewater, leveraging its proximity to both Brickell and Wynwood, is also seeing an upward trajectory for new office and mixed-use developments, positioning itself as a hybrid option.
Talent Acquisition and Infrastructure Headwinds
While Miami offers a compelling value proposition for businesses relocating from higher-tax states, the full cost of operations extends beyond the office lease. The data on residential affordability, particularly for middle-income earners, continues to present a significant challenge for talent acquisition and retention. The average rent for a two-bedroom apartment in Miami-Dade now stands at a level that can deter mid-career professionals, especially those relocating without executive-level compensation packages.
Infrastructure is another critical factor. Increased corporate presence translates to greater demands on transportation networks, existing public utilities, and the local workforce ecosystem. While significant capital is being deployed into infrastructure projects, the pace of corporate relocation often outstrips the immediate capacity of the existing system. Companies weighing a move must factor in not just the office space, but also the long-term viability of attracting and retaining a diverse talent pool within an increasingly expensive and congested urban environment. Climate resilience, too, is moving from a peripheral concern to a core diligence item for institutional players.
Latin American Capital and Synergistic Growth
It’s critical to contextualize the domestic corporate relocations within Miami’s existing strength as a gateway to Latin America. The influx of U.S. firms, particularly in finance and tech, is not occurring in a vacuum. These new entrants are often finding synergies with established Latin American capital flows and business networks. Many U.S. financial firms, for instance, are leveraging their Miami outposts to deepen their reach into Latin American markets, while tech companies find a ready pool of bilingual and bicultural talent with experience in cross-border operations.
This dynamic creates a compounding effect, where domestic relocations reinforce Miami's role as the hemisphere's business hub, attracting further international investment and business activity. This synergy is particularly evident in Brickell, where the concentration of wealth management and private banking caters to both the new domestic arrivals and the perennial demand from Latin American HNWIs.
The data unequivocally demonstrates that corporate relocations to Miami are a tangible force reshaping specific submarkets. However, the narrative needs tempering: it's a targeted, high-impact phenomenon primarily affecting Class A office and bespoke creative spaces. The resulting pressures on affordability and infrastructure are real and must be integrated into any forward-looking market strategy. For those operating within this market, understanding these granular dynamics—rather than simply celebrating aggregate growth—is paramount for informed decision-making.
